
Holding Court is a column by retired Rye City Court Judge Joe Latwin. Latwin retired from the court in December 2022 after thirteen years of service to the City. Latwin appeared on Episode 8 of Season 1 of our podcast MyRye.com Conversations with Doug French. Listen to learn more about Latwin and the Rye City Courts.
What topics do you want addressed by Judge Latwin? Tell us.
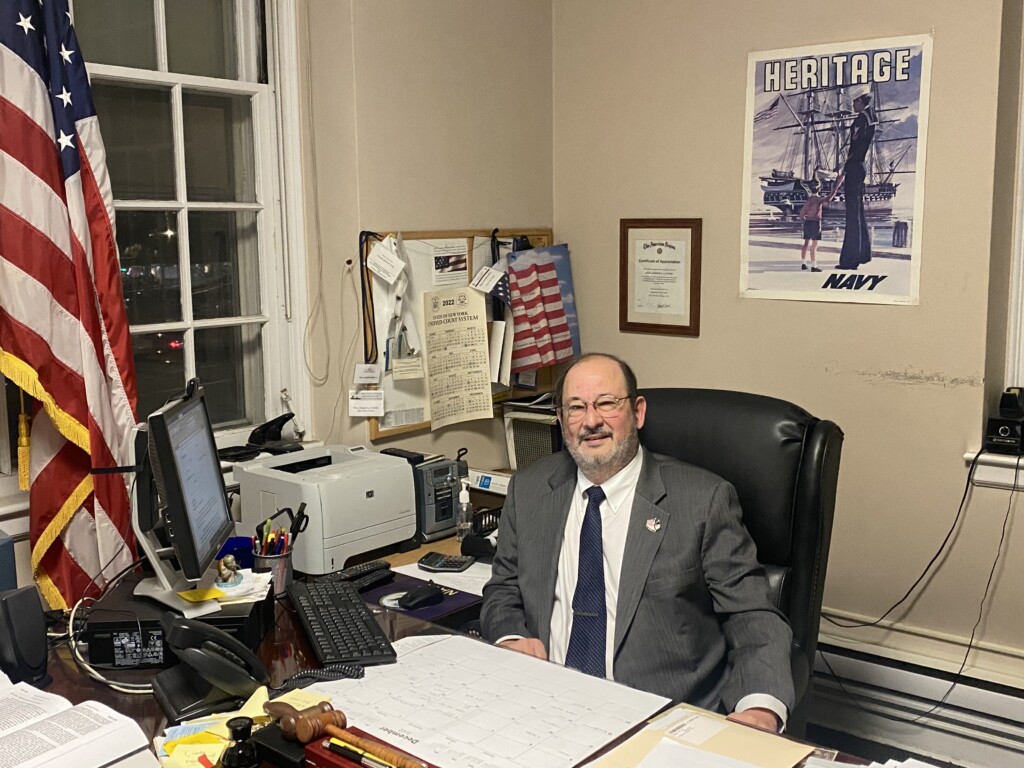
A rose by any other name
Do you have a Roth IRA? Do you know who William Roth was? Do you care, as long as growth within the Roth IRA is not currently taxed as income?
Now there is a new account offering free money and deferring taxes. Let’s call them 530 accounts for the time being.
If you are not 18 by the end of the year and have a Social Security number you are eligible to have a 530 account. If you were born between 2025 and 2028, the Treasury will fund your 530 account with $1,000. To claim the $1,000, the account must be opened by a parent, guardian, adult sibling or a grandparent. The amount contributed by others cannot exceed $5,000 a year. Until the end of the year the beneficiary turns 18 years old, the account must be invested in a mutual fund or an ETF that tracks an index of funds that tracks primarily U.S. companies, does not use leverage, and has an expense ratio of .1% or less. The money in the account can’t be distributed except for qualified rollovers. After the end of the year beneficiary reaches 18, the rules of the account become the same as IRA rules and can be converted to a Roth IRA, attractive since most young adults are often in low tax brackets.
If the parents contribute $5,000 a year, the account will grow to about $320,000 when the beneficiary turns 19 (assuming a 10% return). All the growth above $108,000 (the annual $5,000 plus a 2% inflation adjustment) will be taxable on a conversion to a Roth IRA but this can be spread out to limit jumping into higher tax brackets.
If the kid is under 19 or 24 if they are students, tax is paid at the parents’ tax rate, so they are probably better off waiting until they are not subject to the kiddie tax and when they can take their own standard deduction.
Income and gains received within an IRA are not currently taxable. No distributions are required in a Roth IRA, and until the beneficiary reaches 73 years of age for a traditional IRA. Assuming a 10% growth, by age of 73, the IRA should be worth about $70 million dollars!
Gifts to 530 accounts will not trigger a gift tax if the donor is an individual, the total gifts to any one person do not exceed $19,000 a year, and there are no generation skipping tax implications. If those conditions are met, no gift tax return is needed.
If this type of account sounds like a good deal, would you use it if it wasn’t called a 530 account, but rather a Latwin account? How about if it was called a Trump account? Would you not take advantage of it because of its name? A Roth by any other name . . .