
Holding Court is a column by retired Rye City Court Judge Joe Latwin. Latwin retired from the court in December 2022 after thirteen years of service to the City. Latwin appeared on Episode 8 of Season 1 of our podcast MyRye.com Conversations with Doug French. Listen to learn more about Latwin and the Rye City Courts.
What topics do you want addressed by Judge Latwin? Tell us.
When will you still feed me when I’m 62…63…64….65…66…70?
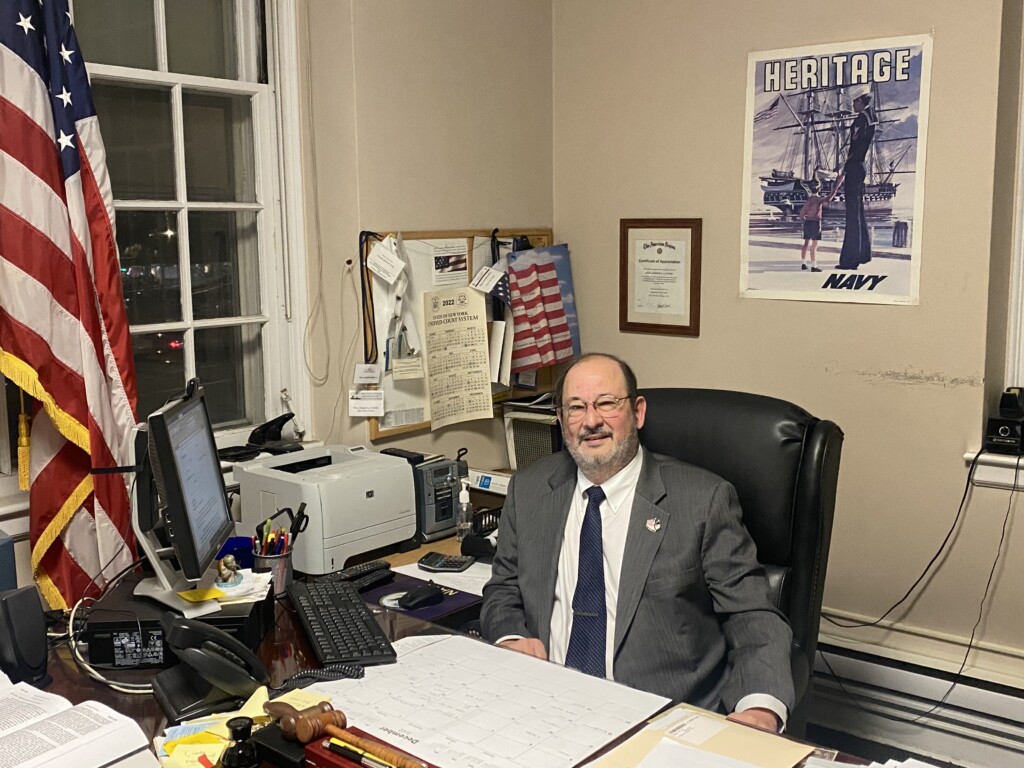
When you get older, losing your hair (too late) many years from now, you’ll have to decide when to apply to start Social Security retirement benefits. Age 62 is the earliest you can begin Social Security retirement benefits. While you can start Social Security retirement benefits at age 62, doing so permanently reduces your monthly payment—typically by 25–30% compared with waiting until full retirement age (“FRA”) (66–67 depending on birth year). If you were born after 1964, your full retirement age is 67. If you would otherwise be eligible for a $2,000/month benefit, retirement at 62 would get you only $1,400/month. This is based on a reduction of 5/9 of 1% for each of the first 36 months before full retirement age, then 5/12 of 1% for additional months.
By taking your Social Security benefit early, you’ll also get less from future Social Security cost-of-living adjustments (COLA). If the COLA is x%, you’ll get that percentage on a smaller number. This smaller number will compound as time goes on as the next year’s COLA will be based on the benefit plus x% plus the next year COLA. If your benefit is 2,000 a month and the COLA is 3%, the next year’s COLA will be based on $2,060. This reduction will persist. Also, while you may apply while you are still working, earnings before FRA may temporarily reduce payments.
Nevertheless, applying at age 62 may make sense for you if you: (1) expect a shorter lifespan (if you’re in poor health and fear you won’t reach full retirement age, you might decide to take your benefits early instead. This might be an easier decision if you’re single and don’t have to worry about the impact on your surviving spouse). (2) You need income immediately (your bills and expenses won’t wait until you’re 70), or you are coordinating spousal benefits (when you file for retirement benefits, your spouse is typically eligible for a benefit based on your earnings, which can be half of your primary benefit amount — depending on your age at retirement. If your spouse begins receiving benefits before FRA, they’ll receive a reduced benefit), or (3) you fear the Social Security funds will run out before you are 70. According to a recent survey, retirees are concerned that Social Security “will not be there for me” when they’re ready to retire. This number is even higher (75%) for women. Overall, fears of cuts in Social Security benefits are high (87%), with most anticipating reductions.
On the other hand, you can delay seeking retirement benefits. Waiting until you are 70 will grow your monthly benefit by at least 24% if your full retirement age is 67, That works out to an 8% increase for every year you delay past your FRA. If your monthly benefit would be $2,000 at age 62, waiting until age 70 to claim benefits will start you at a $3,071 monthly benefit. Of course, COLAs would be larger since the base amount to which the percentage increase would apply would also be larger. The break-even age, where waiting starts to pay off, is typically around 80 to 82. The increased benefits would last for the rest of your life during which Social Security would pay you. For the best deal, live a very long time! Of course, we will still need you and still feed you when you’re 64…65…70.